Last Updated: October 26, 2026
Quick Summary
A tax digital strategy is the plan that connects your accounting systems, records, and filing calendar into one workflow you can maintain. It replaces the annual scramble with a routine, reducing missed receipts, surprise balances due, and time lost to reconstruction. Start by assessing your current operations before buying any software.
- Score your records, account separation, timing, and handoffs; any no is a process gap, not a software gap.
- Set measurable objectives like closing the books within ten days of month-end, not vague goals like getting organized.
- Map every step from purchase to filed return, cut redundant steps, then automate the repetitive parts.
- Limit each system to the people who need it, and confirm you control and can export your data.
- Sequence implementation: separate accounts and capture receipts first, then monthly close, then quarterly reviews.
Table of Contents
- What a Tax Digital Strategy Actually Changes
- Assess Your Current Tax Operations Before Buying Anything
- Set Objectives, Priorities, and Milestones That Fit Your Business
- Redesign Tax Processes Around Automation and Clean Data
- Build a Tax Record Organization System You Will Actually Keep
- How Proactive Tax Planning Fits Into the Digital Workflow
- Small Business Tax Planning: Sequencing the Implementation Roadmap
- Crypto Bookkeeping and Data Governance for Digital Asset Records
- Frequently Asked Questions
What a Tax Digital Strategy Actually Changes
A tax digital strategy is the plan that connects your accounting systems, records, and filing calendar into one workflow you can actually maintain.
The shift is not about buying software. It is about deciding what data you need, where it lives, and who touches it.
That matters more each year as income streams multiply, payment platforms issue more information returns, and digital asset activity adds records that have to be tracked from day one.
Below, we break down how to assess your current setup, set priorities, and sequence the work.
Assess Your Current Tax Operations Before Buying Anything
Start with an honest audit, not a shopping list. Most owners skip this step and buy tools that solve problems they do not have.
Score yourself on four basics:
- Records: Can you produce a receipt for any business expense within five minutes?
- Separation: Are business and personal accounts fully separate?
- Timing: Do you know your tax position before quarter-end, or after?
- Handoffs: When records move between you, a bookkeeper, and your tax preparer, does anything get lost or re-entered by hand?
Any “no” is a process gap, not a software gap. Fix the process first.
A year-round system for recordkeeping and quarterly planning gives you a benchmark to measure against. Our guide to managing business taxes year round walks through a seven-step routine you can compare your current habits to.
Set Objectives, Priorities, and Milestones That Fit Your Business
Objectives should be measurable and small enough to finish. “Get organized” is not an objective. “Close the books within ten days of month-end” is.
A practical way to set them is to work backward from three questions:
- What decision do you need to make this year that you cannot make now because the numbers are not current?
- What recurring task consumes the most hours each month?
- What single gap, if closed, would remove the most year-end stress?
Your answers point to two or three priorities. Resist the urge to list ten. A common pattern among small businesses is that the first two priorities unlock the rest, and the rest can wait a quarter.
Turn priorities into milestones with owners and dependencies
A milestone is only useful if it has an owner, a date, and a definition of done. The table below is a template you can adapt.
| Priority | Milestone | Owner (role) | Depends on | Definition of done | Target timing |
|---|---|---|---|---|---|
| Separate accounts | Business account open, all income and expenses routed through it | Owner | Bank onboarding | No personal transactions in business account for one full month | Month 1 |
| Digital receipts | Every purchase captured same day | Bookkeeper | Receipt tool selected | 95% of transactions have an attached receipt at month-end | Month 1-2 |
| Monthly close | Books closed within 15 days of month-end | Bookkeeper | Clean bank feeds | Three consecutive closes within the target | Month 2 onward |
| Quarterly review | Tax position checked before each due date | Owner + preparer | Monthly close stable | Written estimate review completed before each due date | Every quarter |
| Data governance | Written access and retention rules in place | Owner | Tool inventory | Document listing who can access what, and for how long | Month 3 |
Two things make this table work. First, the “depends on” column exposes sequencing problems before they cost you a month. Second, the “definition of done” column turns a hope into a test you can pass or fail.
Measure progress, not activity
Pick a small set of measures and review them monthly. Useful ones include:
- Percentage of transactions with a receipt attached at month-end
- Days from month-end to closed books
- Number of accounts or systems feeding the books
These are diagnostic, not scorekeeping. If the receipt percentage drops, the capture habit is slipping. If days-to-close rises, a new data source is probably unintegrated.
Redesign Tax Processes Around Automation and Clean Data
Automation only pays off when the data going in is clean. Feed a messy system into a good tool and you get faster mess. The redesign work is therefore mostly about data and controls, and only partly about software.
Map the process before you touch a tool
Start by mapping every step from purchase to filed return. For each step, record four things: what triggers it, who does it, what system it touches, and what can go wrong.
A useful test for each step is to ask whether it produces a record that a reviewer could follow a year later. If not, the step is either redundant or undocumented.
Redesign in this order
- Map every step from purchase to filed return
- Cut steps that exist only because someone always did them
- Standardize the data format at each handoff (dates, vendor names, account codes)
- Automate the repetitive parts: receipt capture, bank feeds, invoice reminders
- Add controls around anything that touches a tax figure
- Document the new process so it survives a busy season
The PwC analysis of tax automation describes a company that automated 80% of its tax compliance processes and saw quick wins. The lesson is not the percentage. It is that automation followed process design, not the other way around.
Data governance belongs in the redesign, not after it
Tax data is sensitive, and the redesign is the moment to decide who can see it, where it lives, and how long you keep it. Three decisions cover most of the risk:
- Access: limit each system to the people who need it, and remove access when a role changes. Shared logins defeat this.
- Retention: decide how long you keep source documents and backups, and where. A consistent retention rule is easier to follow than a case-by-case judgment.
- Ownership: confirm that you, not a vendor, control the underlying data and can export it. Ask this before you sign, not after.
These are governance choices, not technical ones, and they are cheaper to make at redesign time than to retrofit later.
Choose technology that fits the team you have
A neutral selection framework keeps you from buying more tool than you can run. Score candidates on five criteria:
| Criterion | What to check |
|---|---|
| Integration | Does it connect to your bank, accounting system, and payroll without manual exports? |
| Security | Access controls, encryption, and a clear data-ownership statement |
| Scalability | Will it still fit if volume doubles or you add an entity? |
| Support | Written support channels and a clear response expectation |
| Interoperability | Can you export your data in a usable format if you leave? |
A tool that scores well on features but poorly on integration and export will cost you more in manual work than it saves. The same logic applies to crypto records, where exchange and wallet exports vary widely in format and completeness.
Plan for people, not just systems
Process redesign changes roles. The person who used to key in receipts may now review exceptions. The owner who used to approve everything may now review a monthly dashboard. Name the role changes, write short instructions for each, and check adoption at the monthly review.
If you are weighing tools to support this, our comparison of digital tax solutions covers what to look for in year-round planning and document organization.
Build a Tax Record Organization System You Will Actually Keep
A tax record organization system is a simple, repeatable filing habit that keeps every document findable months later.
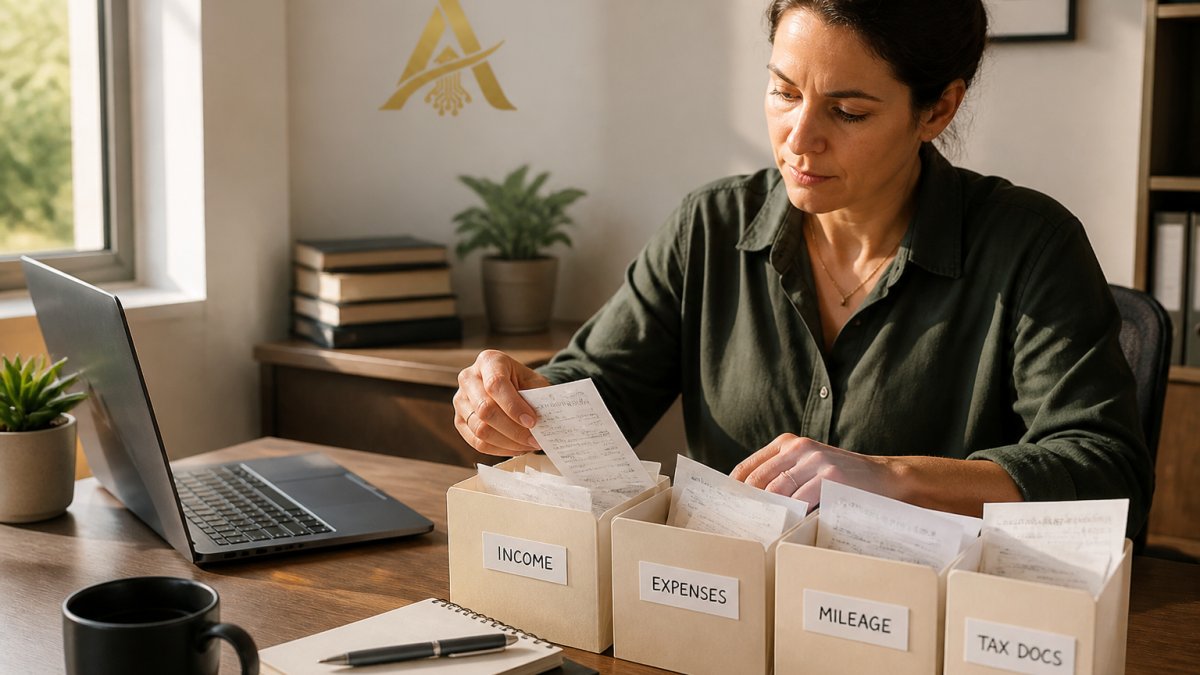
- One folder per tax year, with subfolders for income, expenses, payroll, and assets
- Digital capture at the moment of the transaction, not at tax time
- A monthly review that takes under thirty minutes
Name files with a date first: 2026-03-14 invoice vendor name. Sorting works when names are consistent.
The Thomson Reuters Institute’s 2026 State of Tax Professionals Report surveyed more than 600 tax professionals worldwide and found the field leaning on technology and innovation to handle rising complexity.
How Proactive Tax Planning Fits Into the Digital Workflow
Proactive tax planning means making decisions with your tax position already in view, not discovering it in April. Digital records make that possible because the numbers are current.
Three places it pays off:
- Before you realize a large gain, you can see the tax impact
- Before you sign a contract, you can model the cash flow
- Before year-end, you can adjust estimates instead of reacting
Our Meridian Tax Strategy System supports year-round alignment and planning based on real-time numbers rather than estimates.
Small Business Tax Planning: Sequencing the Implementation Roadmap
Small business tax planning works best in sequence. Trying to fix everything at once is why most overhauls stall by month two.
Here is one possible order:
- Separate accounts and capture receipts. Nothing else works until money flows are clean.
- Set a monthly close. Ten days after month-end is a realistic target.
- Add quarterly estimate reviews. Check your position before each due date.
- Review entity structure. Ask whether your current structure still fits your income.
- Add planning sessions. Model decisions before you make them.
- Automate what is now routine. Only after the process is stable.
Each step builds on the one before. Skipping ahead usually means redoing work.
Crypto Bookkeeping and Data Governance for Digital Asset Records
Crypto records fail for one reason: missing or incomplete data. Not tax rates. Not strategy. Missing records.
Digital asset reporting requires a clear trail for every transaction: date, amount, cost basis, and wallet.
Build the record habit first:
- Export exchange and wallet history monthly
- Track cost basis at the time of acquisition, not later
- Keep a running log of staking, airdrops, and DeFi activity
Our crypto and digital asset recordkeeping checklist lays out the documents to keep. Crypto bookkeeping and reconciliation starts with a $95 Crypto Review. The $95 is non-refundable and fully credited toward your engagement if it begins within 30 days.
Watch out: reconstructing cost basis a year later is far harder than logging it as you go.
Frequently Asked Questions
What does a tax digital strategy mean for a small business?
It means running tax work on a system instead of a scramble. You connect bookkeeping, document storage, and reporting so income and expenses are captured as they happen, not reconstructed in April. A practical tax digital strategy sets objectives, picks a few tools that talk to each other, and assigns who does what each month. The goal is organized records and a clearer understanding of tax impact before you sign a contract or sell an asset. Start with your current books, then add automation one process at a time.
How can digital tools support year-round proactive tax planning?
Proactive tax planning depends on current numbers. When bookkeeping is updated monthly and records are organized in one place, you can review estimated tax impact before a big invoice, a large purchase, or an asset sale. Digital tools can help organize records and make current numbers available for review. The tools do not make decisions for you; they shorten the lag between a business event and your understanding of its tax effect.
What records should a business organize for tax planning?
At minimum: bank and credit card statements, sales records, expense receipts, payroll reports, contractor payments, loan documents, and asset purchase records. Digital asset investors should also keep exchange statements, wallet addresses, and transaction histories for staking, swaps, and NFT sales. Good tax record organization means one consistent folder structure, clear file names, and a monthly reconciliation habit. Store records in a location with access limited to the people who need them.
How can digital asset investors organize transaction records for tax reporting?
Keep transaction histories and supporting statements for exchanges and wallets, including records of cost basis, transfers, staking rewards, and sales. Clean records make it easier to understand tax impact before you realize a gain and give your tax preparer a complete picture.
Most owners do not need more software. They need a sequence, a record habit, and a planning rhythm that holds up past January.
That is what we build at All Digital Tax. Our work pairs the Meridian Tax Strategy System with crypto-ready bookkeeping, so your records and your planning stay in step. You get organized financials and a clear view of tax impact before you make a decision, not after.
Get Started Today and put a tax digital strategy in place that you will still be running next year.
